



Understanding Freelancer Status in Canada
Key Takeaways
- Register with CRA immediately upon starting freelance work to ensure proper tax compliance
- Maintain separate business banking accounts to simplify expense tracking and reporting
- Set aside 25-30% of income quarterly for tax obligations including CPP contributions
- Understand GST/HST registration requirements based on $30,000 annual revenue threshold
- Consider incorporation once earning consistently above $60,000 annually for tax efficiency benefits
Defining self-employment vs employment status
When I started my freelance journey in Canada, I quickly learned that understanding my employment status was crucial. The Canada Revenue Agency makes clear distinctions between employees and self-employed individuals. As freelancers, we control our work methods, use our own tools, and bear financial risks. This classification affects everything from tax obligations to pension contributions and determines whether we need to register for GST/HST based on our annual revenue thresholds.
The legal framework for freelancers requires us to operate as independent contractors rather than employees. This means we’re responsible for managing our own business operations, including invoicing clients directly and maintaining proper financial records. We must understand that being self-employed gives us flexibility, but also places the burden of compliance squarely on our shoulders without employer support systems.
Legal requirements for operating as a freelancer
Operating legally as a freelancer in Canada involves several mandatory steps that protect both our business and personal interests. We need to register with the appropriate provincial authorities if operating under a business name different from our personal name. Many provinces require business name registration through their corporate registries, which helps establish our professional identity while ensuring legal compliance across jurisdictions.
We must also obtain necessary business numbers from the CRA for tax purposes and consider professional liability insurance depending on our industry. Understanding provincial regulations on contracts, client agreements, and dispute-resolution mechanisms is essential to protecting our interests when working with Canadian or international clients across different legal frameworks.
Determining your business structure (sole proprietorship, corporation)
Choosing the right business structure fundamentally impacts how we manage taxes, liability, and growth potential as Canadian freelancers. Most of us start as sole proprietors because it’s easy to set up with minimal paperwork and lower initial costs. However, this structure offers no separation between personal and business assets, meaning creditors can pursue personal property if business debts accumulate unexpectedly.
Incorporating provides significant advantages, including limited liability protection and potential tax benefits through income splitting opportunities. The corporate tax rate is often lower than personal income tax rates for higher earners, though it involves more complex accounting requirements and annual filing obligations. We should consult professionals about tax structuring strategies that align with our long-term financial goals while maintaining compliance with Canadian regulations.
Essential Tax Planning for Remote Freelancers
Calculating estimated tax obligations
We calculate our estimated tax obligations by projecting annual income and applying federal and provincial tax rates. I recommend setting aside 25-30% of each payment for taxes, which covers both income tax and Canada Pension Plan contributions. This proactive approach prevents cash flow surprises and ensures we meet our quarterly instalment requirements. Understanding our marginal tax brackets helps us make strategic decisions about income timing and business expense planning throughout the year.
Our tax planning strategy involves quarterly instalment payments due March 15, June 15, September 15, and December 15. We use the CRA’s instalment reminders to guide our payment amounts, but many freelancers prefer calculating based on current year projections. This disciplined approach avoids interest charges and penalties while maintaining good standing with tax authorities. We track all income sources meticulously to ensure accurate quarterly calculations.
Setting aside funds for quarterly tax payments
We maintain a separate high-interest savings account specifically for tax obligations, transferring funds immediately upon receiving client payments. This segregation prevents accidental spending of money earmarked for taxes and provides clear visibility into our financial position. Our system ensures we always have sufficient funds available when quarterly instalment deadlines approach, eliminating last-minute stress and potential cash shortages.
Our practice involves calculating tax reserves based on progressive tax brackets and provincial rates applicable to our location. We adjust these percentages quarterly based on actual income performance and changing business circumstances. This dynamic approach allows us to optimise cash flow while remaining compliant with CRA requirements. Regular review of our tax reserve strategy ensures we’re neither over-saving nor under-preparing for tax obligations.
Understanding tax brackets and rates for freelancers
We navigate Canada’s progressive tax system where federal rates range from 15% to 33%, plus provincial rates that vary significantly across jurisdictions. Understanding these brackets helps us make informed decisions about income splitting, business structure selection, and retirement planning. Our knowledge of marginal tax rates enables strategic timing of large purchases and business investments to maximise tax efficiency throughout the fiscal year.
We carefully monitor changes to tax brackets and rates announced in federal and provincial budgets each year. This proactive approach ensures our tax planning remains current and optimised for changing legislative environments. Our understanding of how different income levels interact with various tax credits and deductions allows us to structure our business activities for maximum after-tax retention of earnings.
Income Tax Filing Procedures
Completing Form T2125 Statement of Business Activities
We complete Form T2125 annually to report all freelance income and business expenses to the Canada Revenue Agency. This comprehensive form captures our gross business income, cost of goods sold, and detailed expense categories. Our meticulous record-keeping throughout the year makes this process straightforward, ensuring we claim all legitimate business deductions while maintaining compliance with CRA requirements.
Our approach to Form T2125 involves categorising expenses according to CRA guidelines, including home office costs, vehicle expenses, professional fees, and business-related travel. We maintain supporting documentation for all claimed expenses, understanding that proper record-keeping is essential for audit protection. This disciplined process ensures accurate reporting and maximises our legitimate tax deductions.
Reporting freelance income accurately
We report all freelance income received during the tax year, including payments from Canadian and international clients. Our system tracks income by client and project, ensuring comprehensive reporting that matches our business records. We understand that accurate income reporting is fundamental to maintaining good standing with tax authorities and avoiding potential penalties for under-reporting.
Our income reporting process includes reconciling all payment platforms, bank deposits, and client invoices to ensure no income is overlooked. We maintain detailed records of payment dates, amounts, and client information to support our tax filings. This thorough approach provides confidence that our tax returns accurately reflect our business activities and financial performance.
Filing deadlines and payment schedules
We adhere to the June 15 filing deadline for self-employed individuals, though any taxes owed must be paid by April 30 to avoid interest charges. Our system ensures we meet both deadlines consistently, with tax payments processed well in advance of due dates. This disciplined approach prevents unnecessary interest costs and maintains our positive relationship with tax authorities.
Our payment schedule aligns with CRA instalment requirements for self-employed individuals who expect to owe more than $3,000 in taxes for the year. We make quarterly payments based on either prior year tax liability or current year projections, whichever method provides the most accurate estimate. This strategic approach optimises our cash flow while ensuring full compliance with tax payment obligations.
Sales Tax Management for Freelancers
Sales Tax Management for Freelancers
GST/HST registration requirements
We register for GST/HST once our annual freelance revenue exceeds $30,000, though voluntary registration can provide tax efficiency benefits even below this threshold. Our registration process involves obtaining a business number from the CRA and understanding our specific provincial harmonised sales tax requirements. This proactive approach ensures we remain compliant with sales tax legislation while optimising our business operations.
Our GST/HST registration strategy considers both mandatory thresholds and voluntary registration advantages, including the ability to claim input tax credits on business expenses. We carefully evaluate whether early registration aligns with our business growth plans and client expectations. This thoughtful approach to sales tax registration supports both compliance and strategic business development objectives.
Charging and collecting sales tax from clients
We charge the appropriate GST/HST rates based on client location and the nature of services provided, with careful attention to provincial variations. Our invoicing system automatically calculates and applies the correct sales tax amounts, ensuring accurate billing and proper documentation. This systematic approach prevents errors in tax collection and maintains professional standards with our clients.
Our sales tax collection process includes clear communication with clients about tax-inclusive pricing and proper invoice breakdowns. We maintain detailed records of all tax collected, organised by reporting period and client jurisdiction. This meticulous approach ensures we can accurately report and remit collected taxes while providing transparent billing to our clients.
Filing GST/HST returns
We file GST/HST returns according to our assigned reporting period, typically annually for smaller businesses but potentially quarterly or monthly for higher-volume operations. Our filing process involves reconciling collected sales tax against eligible input tax credits for business expenses. This careful calculation ensures we remit the correct net amount to the CRA while maximising our legitimate tax recoveries.
Our GST/HST return preparation includes comprehensive review of all business expenses to identify eligible input tax credits, from office supplies to professional services. We maintain supporting documentation for all claimed credits, understanding the importance of proper record-keeping for audit protection. This disciplined approach to sales tax management supports both compliance and financial planning objectives.
Canada Pension Plan Contributions
CPP contribution calculations for self-employed individuals
We calculate our Canada Pension Plan contributions differently from traditional employees because we’re responsible for both the employer and employee portions. As self-employed freelancers, we pay the full 11.9% rate on our net business income up to the annual maximum pensionable earnings. This means we contribute double what employed individuals pay, but it’s essential for building our retirement security. The calculation begins with our net self-employment income from our T2125 form, and we must track this throughout the year to ensure accurate contributions.
Understanding the CPP enhancement that began in 2024 is crucial for our financial planning. Now we have two tiers of contributions: the base CPP amount and first additional contributions up to the first earnings ceiling, plus CPP2 contributions on earnings above that threshold. This progressive system means higher earners contribute more to receive enhanced benefits later. We need to calculate these separately and ensure we’re setting aside the correct amounts throughout the year to avoid surprises at tax time.
Employer vs employee CPP contributions
When we work as traditional employees, our employers match our CPP contributions dollar-for-dollar, effectively splitting the 11.9% total rate. However, as self-employed individuals, we bear the entire burden ourselves. This distinction is critical for our cash flow management and tax planning. We must remember that while employed individuals see only 5.95% deducted from their paycheques, we need to budget for the full amount from our business income.
The employer-employee contribution split doesn’t exist in our world, which means we’re essentially paying both sides of the equation. This reality affects our net income calculations and requires careful financial planning. We should view this as an investment in our future retirement security rather than simply a tax burden. Properly managing these contributions ensures we maximise our eventual CPP benefits while maintaining compliance with Canadian tax laws.
Maximising your CPP benefits
To maximise our Canada Pension Plan benefits, we need to contribute consistently throughout our working years and understand how the calculation works. The amount we receive in retirement depends on our contributions, the number of years we contributed, and when we start receiving benefits. We should aim to contribute as much as possible each year to build the highest possible retirement income. This requires careful income management and strategic business planning.
We can enhance our CPP benefits by delaying receipt beyond age sixty-five, which increases our monthly payments by 0.7% for each month we delay, up to age seventy. Additionally, we should ensure we’re taking advantage of all eligible income sources that count toward CPP calculations. Proper record-keeping and timely contributions are essential for building our retirement security through the Canada Pension Plan system as self-employed professionals.
Business Expense Deductions
Common deductible business expenses
We can deduct numerous business expenses directly related to earning our freelance income, thereby significantly reducing our taxable income. Common deductible expenses include office supplies, professional fees, marketing costs, software subscriptions, and business insurance premiums. These deductions help lower our overall tax burden while supporting our business operations. We must ensure all expenses are reasonable and directly connected to our income-generating activities.
Professional development costs, including courses, conferences, and certifications that maintain or improve our skills, are fully deductible. Business-related travel expenses, meals with clients, and home office costs also qualify when properly documented. We need to maintain detailed records and receipts for all deductible expenses to support our claims during potential CRA reviews. Understanding which expenses qualify helps us maximise our deductions legally and efficiently.
Home office expense calculations
Calculating home office expenses requires careful measurement and documentation of the space we use exclusively for business purposes. We can deduct a portion of our rent or mortgage interest, property taxes, utilities, and home insurance based on the percentage of our home used for business. The calculation typically involves dividing the square footage of our workspace by the total square footage of our home. This percentage then applies to our eligible home expenses.
We have two methods for claiming home office expenses: the detailed method or the temporary flat rate method introduced during COVID-19. The detailed method requires meticulous record-keeping but often yields higher deductions for a dedicated workspace. We must ensure our home office is our principal place of business or used exclusively for earning income. Proper calculation and documentation protect us during CRA audits while maximising our legitimate business deductions.
Vehicle, equipment, and professional development deductions
Vehicle expenses for business purposes are deductible when we maintain detailed mileage logs separating personal and business use. We can choose between the detailed method, which tracks actual expenses, or the simplified method, which uses the CRA’s prescribed rates. Business equipment purchases, including computers, cameras, and specialised tools, can be deducted immediately or capitalised and depreciated over time. Understanding the difference helps our cash flow management.
Professional development expenses, including courses, workshops, and industry publications, are fully deductible when they maintain or improve skills required for our current business. Conference attendance, professional association fees, and certification costs also qualify. We should track all these expenses throughout the year and maintain supporting documentation. These deductions not only reduce our tax liability but also support our business growth and professional development.
Banking Solutions for Freelancers
Choosing the right business bank account
Selecting the appropriate business bank account is fundamental for separating our personal and business finances effectively. We need accounts that offer low fees, convenient digital access, and features tailored to the income patterns of freelancers. Many Canadian banks now provide specialised accounts for self-employed individuals with reduced transaction fees and integrated expense tracking. We should compare account structures across different financial institutions to find the best fit.
Digital-only banks often offer superior features for remote freelancers, including lower fees, higher interest rates, and better international transaction capabilities. However, traditional banks provide comprehensive services and physical branch access when needed. We must consider our specific banking needs, transaction volume, and preferred access methods. Maintaining separate business accounts simplifies our bookkeeping, enhances professional credibility, and streamlines tax preparation.
Managing cash flow and working capital
Effective cash flow management is crucial for our freelance sustainability, requiring careful monitoring of income timing and expense patterns. We should maintain adequate working capital to cover business operations during slower income periods. Creating detailed cash flow projections helps us anticipate financial needs and avoid liquidity crises. Regular review of accounts receivable and payable ensures we’re managing our business finances proactively.
We can improve our cash flow by establishing clear payment terms with clients, sending invoices promptly, and systematically following up on overdue payments. Building an emergency fund equivalent to three to six months of business expenses provides crucial financial stability. Using accounting software to track income and expenses in real-time helps us make informed financial decisions. Proper cash flow management ensures we can meet our obligations while investing in business growth.
Digital banking tools for remote workers
Modern digital banking tools revolutionise how we manage our freelance finances, offering real-time access and automation capabilities. Mobile banking apps allow us to deposit cheques remotely, transfer funds instantly, and monitor account activity from anywhere. Integration with accounting software like QuickBooks or Wave automates expense categorisation and financial reporting. These tools save time and reduce manual errors in our financial management.
Digital payment platforms facilitate quick invoicing and payment collection from international clients while providing currency conversion services. Expense-tracking apps help us capture receipts digitally and automatically categorise business expenses. We should leverage these technologies to streamline our financial operations and maintain accurate records. Embracing digital banking tools enhances our efficiency and provides valuable insights into our business performance through analytics and reporting features.
Retirement Planning Strategies
RRSP contributions and limits
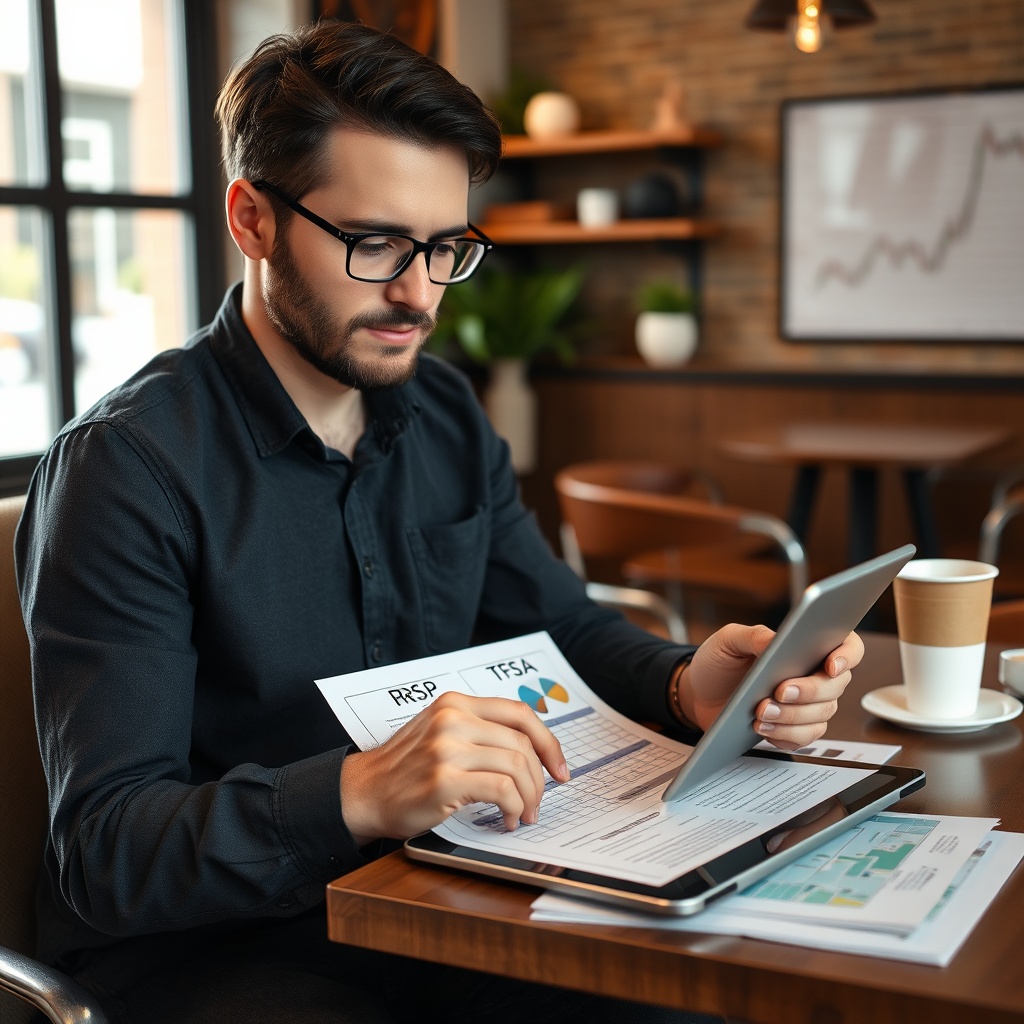
Registered Retirement Savings Plans offer powerful tax advantages for our retirement planning as self-employed Canadians. We can contribute up to 18% of our previous year’s earned income, up to the annual maximum limit, and deduct these contributions from our taxable income. This immediate tax reduction makes RRSPs particularly valuable for higher-income years. We should prioritise maximising our RRSP contributions to build tax-sheltered retirement savings efficiently.
Understanding our contribution room requires checking our Notice of Assessment each year, as the unused room carries forward indefinitely. We can contribute to our RRSP until December 31st of the year we turn 71, providing decades of tax-deferred growth potential. Strategic timing of strategic contributions can optimise our tax situation, especially during high-income years. Regular contributions, even in smaller amounts, compound significantly over time through tax-free investment growth within the plan.
Tax-Free Savings Accounts (TFSAs)
Tax-Free Savings Accounts complement our RRSP strategy by providing completely tax-free growth and withdrawals, making them ideal for flexible retirement planning. Unlike RRSPs, TFSA contributions aren’t tax-deductible, but all investment income and capital gains accumulate tax-free. We can withdraw funds at any time without tax consequences, and the withdrawal amount adds back to our contribution room the following year. This flexibility supports various financial goals beyond retirement.
Our TFSA contribution room accumulates annually from the year we turned 18, regardless of income level or employment status. Unused contribution room carries forward indefinitely, allowing us to make catch-up contributions when financially feasible. We should consider TFSAs for medium-term savings goals and as part of our overall retirement income strategy. The combination of RRSPs and TFSAs provides comprehensive tax planning opportunities for our self-employed retirement needs.
Additional retirement savings options
Beyond RRSPs and TFSAs, we have several additional retirement savings vehicles to consider based on our financial situation and goals. Individual pension plans offer enhanced contribution limits for incorporated professionals, while non-registered investment accounts offer complete flexibility with no contribution limits. Real estate investments, particularly rental properties, can generate retirement income while building equity over time. Diversifying across multiple asset types enhances our retirement security.
We should also consider incorporating our business to access small business deduction rates and create additional retirement planning opportunities through corporate investment strategies. Professional corporations allow for the establishment of pension plans and income splitting. Consulting with financial advisors specialising in self-employed retirement planning helps us navigate these complex options. A comprehensive approach combining multiple strategies ensures we build adequate retirement resources while optimising our current tax situation.
Record Keeping and Documentation
Essential financial records to maintain
We maintain meticulous records because the CRA requires us to keep detailed documentation for at least six years. Our system includes invoices, receipts, bank statements, and expense tracking. We organise everything chronologically and categorise expenses properly for easy retrieval. This disciplined approach ensures we can substantiate every deduction claimed and income reported. Proper record keeping transforms tax season from stressful to straightforward.
Our record-keeping strategy involves maintaining both digital and physical copies of essential documents. We track all business income through detailed invoicing systems and monitor expenses using dedicated software. This comprehensive approach helps us identify cash flow patterns and make informed financial decisions. We’ve learned that organised records are our first line of defence during CRA audits and reviews.
Digital tools for expense tracking
We leverage modern digital tools to streamline our expense tracking and financial management. Cloud-based accounting software helps us capture receipts instantly via mobile apps and automatically categorise expenses. These tools provide real-time insights into our business performance and cash flow. We can generate reports quickly and identify tax-saving opportunities throughout the year rather than scrambling at tax time.
Our digital toolkit includes expense tracking apps that integrate with our bank accounts and credit cards. These platforms automatically categorise transactions and flag potential deductions we might otherwise miss. We use project management tools to track billable hours and efficiently invoice clients. This digital ecosystem saves us countless hours and reduces the risk of human error in our financial reporting.
Record retention requirements
We understand that Canadian tax law requires us to retain business records for 6 years from the end of the last tax year to which they relate. This includes all supporting documents for income, expenses, and GST/HST filings. We maintain organised digital archives with proper backup systems to ensure compliance. Our retention policy covers everything from client contracts to bank statements and expense receipts.
Our record retention strategy includes both physical and digital storage solutions with proper security measures. We keep detailed logs of when documents can be safely destroyed in accordance with CRA guidelines. This systematic approach protects us during potential audits and ensures we can promptly provide requested documentation. We’ve implemented automated reminders for document retention periods to ensure effortless compliance.
International Client Considerations
Working with clients outside Canada
We’ve developed specialised strategies for managing international client relationships while maintaining Canadian tax compliance. When working with clients outside Canada, we carefully document the nature of services provided and payment terms. We maintain detailed records of all cross-border transactions and understand how different payment methods affect our reporting requirements. This global perspective helps us serve international markets effectively.
Our approach to international clients includes understanding currency exchange implications and managing foreign income reporting. We track exchange rates at the time of transaction and maintain proper documentation for all foreign payments received. This careful attention to detail ensures we accurately report international income on our Canadian tax returns. We’ve learned that proper documentation is crucial for defending our tax positions.
Cross-border tax implications
We navigate complex cross-border tax implications by understanding how international income affects our Canadian tax obligations. When earning income from clients in other countries, we consider potential tax treaty benefits and foreign tax credit opportunities. Our system includes tracking foreign taxes paid and understanding how they interact with our Canadian tax liability. This comprehensive approach helps us optimise our global tax position.
Our cross-border tax strategy involves maintaining detailed records of all international transactions and understanding reporting thresholds. We monitor changes in international tax laws that might affect our business operations. This proactive approach helps us identify potential compliance issues before they become problems. We’ve found that proper planning makes international business both profitable and compliant.
Professional Financial Guidance
When to seek professional advice
We recognise when the complexity of our freelance business requires professional financial guidance. Significant income changes, international expansion, or complex business structures all prompt us to consult experts. Professional advisors help us navigate intricate tax situations and ensure we’re maximising available deductions. Their expertise becomes particularly valuable during business transitions or when facing CRA inquiries.
Our approach to professional guidance includes establishing relationships with trusted accountants and tax specialists before we need them. We schedule regular check-ins to review our financial strategies and ensure we’re compliant with evolving regulations. This proactive relationship building gives us confidence in our financial decisions and helps us avoid costly mistakes. Professional advice has consistently proven to be a wise investment in our business growth.
Building your professional team
We’ve carefully built a professional team including accountants, tax specialists, and financial advisors who understand the unique needs of freelancers. Each team member brings specific expertise that complements our business operations. Our accountant helps with tax planning and compliance, while our financial advisor focuses on long-term wealth building. This collaborative approach ensures we receive comprehensive guidance across all financial aspects.
Our professional team development strategy involves selecting advisors with experience in the freelance and digital nomad space. We prioritise professionals who understand modern business models and can provide relevant, forward-thinking advice. Regular communication with our team helps us stay ahead of regulatory changes and optimise our financial strategies. This support network has been instrumental in our business success and financial stability.
Strategic Tax Planning
Long-term tax optimisation strategies
We implement long-term tax optimisation strategies that align with our business growth objectives and personal financial goals. Our approach includes strategic timing of income recognition, careful expense planning, and maximising available tax credits. We work with our professional advisors to develop multi-year tax plans that consider both current and future tax implications. This forward-thinking strategy helps us minimise our overall tax burden while remaining fully compliant.
Our tax optimisation framework includes regular reviews of our business structure and income allocation strategies. We monitor changes in tax legislation that might create new opportunities or require adjustments to our approach. This disciplined planning allows us to make informed decisions about business investments and personal financial management. We’ve found that proactive tax planning significantly enhances our financial outcomes over time.
Adapting to regulatory changes
We maintain flexibility in our financial strategies to adapt quickly to regulatory changes and evolving tax requirements. Our system includes regular monitoring of CRA updates and industry best practices. When new regulations emerge, we assess their impact on our business operations and adjust our processes accordingly. This adaptive approach ensures we remain compliant while optimising our financial position under changing rules.
Our regulatory adaptation strategy involves staying informed through professional networks and industry publications. We participate in relevant training and workshops to understand emerging trends in freelance taxation. This continuous learning approach helps us anticipate changes rather than reacting to them. We’ve built systems that can quickly incorporate new requirements without disrupting our core business operations.
International Client Considerations
Working with clients outside Canada
When we work with international clients, we face unique tax implications that require careful planning. We must determine whether our services qualify as export services, which could affect GST/HST obligations. We also need to consider currency exchange rates and their impact on our income reporting. International payments often involve additional banking fees and processing times that we need to account for in our pricing and cash flow management strategies.
We maintain detailed records of all international transactions, including client contracts and payment receipts. This documentation becomes crucial during tax season when we need to report foreign income accurately. We also consider the tax treaties Canada has with other countries to avoid double taxation. Understanding these international aspects helps us expand our client base globally while remaining compliant with Canadian tax laws.
Cross-border payment processing
We’ve learned that managing cross-border payments requires strategic thinking about banking relationships and payment platforms. We prefer using international banking solutions that offer competitive exchange rates and lower transaction fees. Many freelancers use platforms like PayPal, Wise, or Stripe for international payments, but we always compare the costs and processing times. We also consider the timing of currency conversions to maximise our earnings.
We maintain separate tracking for international income to simplify our tax reporting process. This includes recording the date of payment, the exchange rate used, and any fees deducted. We’ve found that setting up dedicated business accounts with international banking capabilities streamlines our payment processing. This approach helps us manage cash flow effectively while ensuring we meet all reporting requirements for foreign income.
Financial Planning for Freelancers
Budgeting for variable income
We’ve developed a systematic approach to managing our variable income that ensures financial stability throughout the year. We calculate our average monthly earnings and base our essential expenses on this conservative estimate. We maintain separate accounts for business operations, tax obligations, and personal expenses. This separation helps us avoid spending money that should be allocated for quarterly tax payments or business expenses.
We create quarterly financial projections that account for seasonal fluctuations in our freelance work. This forward-looking approach allows us to adjust our spending and savings strategies proactively. We also build emergency funds equivalent to three to six months of essential expenses. This financial cushion protects us during slow periods and provides peace of mind as we navigate the uncertainties of freelance income.
Investment strategies for freelancers
We approach investment planning with a focus on both short-term liquidity and long-term growth. We prioritise building our emergency fund before committing to longer-term investments. Once we establish financial stability, we diversify our investments across different asset classes and risk levels. We regularly contribute to our RRSP and TFSA accounts, taking advantage of tax-deferred growth opportunities.
We work with financial advisors who understand the unique challenges of freelance income patterns. They help us develop investment strategies that align with our variable cash flow while maximising retirement savings. We also consider asset allocation strategies that balance risk and return based on our financial goals and timeline. This comprehensive approach ensures we’re building wealth while maintaining financial flexibility.
Insurance and Risk Management
Professional liability protection
We recognise that professional liability insurance is essential for protecting our freelance business from potential claims. This coverage safeguards us against client disputes over the quality of our work or missed deadlines. We carefully review policy terms to ensure adequate protection for our specific services and client types. The cost of this insurance is treated as a deductible business expense and factored into our pricing structure.
We maintain detailed contracts with all clients that clearly outline project scope, deliverables, and liability limitations. These contractual agreements work in conjunction with our insurance coverage to minimise risk exposure. We also keep comprehensive records of all client communications and project documentation. This thorough approach to risk management gives us confidence in our business operations and protects our financial stability.
Health and disability coverage
As freelancers, we must secure our own health and disability insurance since we don’t have employer-provided benefits. We research provincial health coverage options and supplement with private insurance for additional protection. Disability insurance becomes particularly important since our income depends entirely on our ability to work. We calculate appropriate coverage amounts based on our average earnings and essential living expenses.
We regularly review our insurance policies to ensure they remain adequate as our business grows and personal circumstances change. We also consider critical illness insurance as part of our comprehensive risk management strategy. These insurance costs are legitimate business expenses that we deduct from our taxable income. This proactive approach to insurance planning provides essential protection for our health and financial well-being.
Digital Tools and Technology
Accounting software solutions
We leverage modern accounting software to streamline our financial management and tax preparation processes. These tools help us track income, expenses, and tax obligations in real-time. We choose platforms that integrate with our banking institutions and payment processors to automatically record transactions. The software generates detailed reports that simplify our quarterly tax calculations and annual filing requirements.
We utilise cloud-based accounting solutions that allow us to access financial data from anywhere while maintaining secure backups. These systems automatically categorise transactions and flag potential deductible expenses we might otherwise miss. The software also helps us generate professional invoices and efficiently track payment status. This technological approach saves us significant time while improving the accuracy of our financial records.
Project management and productivity tools
We implement comprehensive project management systems that help us organise client work, track deadlines, and manage our workflow efficiently. These tools enable us to maintain clear communication with clients while documenting project progress. We use time-tracking software to accurately bill clients for our work and analyse our productivity patterns. This data helps us optimise our pricing and identify our most profitable service offerings.
We integrate our project management tools with our accounting software for seamless business operations. This integration allows us to generate invoices directly from completed projects and track payment status in one centralised system. We also use digital asset management solutions to organise client files and project documentation securely. These technological investments significantly enhance our operational efficiency and the quality of our client service.
Business Growth Strategies
Scaling your freelance business
We approach business growth strategically by first establishing solid systems and processes before expanding our client base. We focus on developing specialised expertise that allows us to command premium rates for our services. We carefully analyse which types of projects generate the highest returns and align with our long-term goals. This targeted approach helps us grow our business sustainably without compromising quality or work-life balance.
We implement systematic marketing strategies that consistently generate new client opportunities while maintaining relationships with existing clients. We track our marketing efforts to identify the most effective channels for reaching our target audience. We also consider forming strategic partnerships with complementary service providers to expand our service offerings. This growth strategy allows us to scale our business while maintaining the flexibility and independence that attracted us to freelancing.
Diversifying income streams
We actively develop multiple income streams to reduce our reliance on any single client or project type. This diversification strategy includes offering different service packages, creating digital products, and exploring passive income opportunities. We balance our time between client work and developing scalable assets that can generate revenue with minimal ongoing effort. This approach creates financial stability while allowing for creative exploration.
We regularly assess our service offerings and market demand to identify new income opportunities. We invest in continuous learning to expand our skill set and stay current with industry trends. We also consider alternative investment strategies to generate additional income from our business profits. This comprehensive approach to income diversification ensures long-term financial security and business resilience.
Frequently Asked Questions
How much should I set aside for taxes as a Canadian freelancer?
We recommend setting aside 25-30% of each payment received to cover federal and provincial income taxes, as well as both the employer and employee portions of CPP contributions. This percentage may vary based on your income level and province of residence. We maintain separate high-interest savings accounts specifically for tax obligations to avoid spending this money. Regular quarterly instalments help manage cash flow and prevent large tax bills at year-end.
What business expenses can I deduct as a freelancer in Canada?
We deduct legitimate business expenses, including home office costs, equipment purchases, professional development, marketing expenses, and vehicle expenses for business travel. The Canada Revenue Agency requires these expenses to be directly related to earning business income. We maintain detailed records and receipts for all deductible expenses, categorising them properly on Form T2125. Understanding eligible deductions significantly reduces our taxable income.
When do I need to register for GST/HST as a freelancer?
We must register for GST/HST once our annual worldwide revenues exceed $30,000 in any single calendar quarter or over four consecutive quarters. Voluntary registration is possible even below this threshold if it benefits our business. Once registered, we charge, collect, and remit GST/HST on taxable supplies while claiming input tax credits on business purchases. We file regular returns based on our chosen reporting period.
How do I manage retirement planning without employer pension plans?
We take full responsibility for our retirement planning through RRSP contributions, TFSA investments, and additional savings vehicles. We contribute regularly to our RRSPs, taking advantage of tax-deferred growth and deduction benefits. We also maximise TFSA contributions for tax-free investment growth. Diversifying our retirement savings across different account types provides flexibility and tax efficiency in our long-term financial planning.
What banking solutions work best for Canadian freelancers?
We use dedicated business bank accounts that completely separate personal and business finances. We prefer accounts with low fees, good digital banking features, and integration with accounting software. Many Canadian banks offer specialised accounts for small businesses and self-employed individuals with features tailored to our needs. We also utilise digital payment platforms for efficient client billing and international payment processing.
