No spam - just the latest insights!
Join over 30,000 industry professionals who subscribe for free

Subscribe for free!
We'll never share your information or send you spam

Xorse Godzi is Chief Executive and Head of Coverage of Standard Chartered Bank Ghana PLC. A career banker with more than two decades of corporate and investment banking experience across Africa and Europe, his expertise spans client coverage, corporate banking, sustainable finance and the financing needs of businesses operating across key sectors of the economy.
Throughout his career, Xorse has worked with local and multinational corporates across sectors including energy, mining, manufacturing, agriculture, and financial services. This experience has given him a broad perspective on how businesses are responding to evolving environmental, social and governance considerations and the role financial institutions and capital can play in supporting sustainable economic growth and transition.
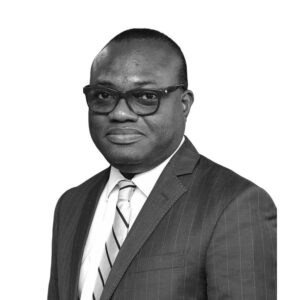
Richard Bram Annor is Head of Financial Institutions at Standard Chartered in Ghana, where he leads the Bank’s relationships with banks, non-bank financial institutions, sovereign and public sector entities, development finance institutions and multilateral organisations.
With experience across financial institutions coverage, debt capital markets, trade finance and strategic advisory, Richard brings a strong understanding of how financial markets can mobilise capital to address economic and development priorities. His work places him at the intersection of institutional capital, sustainable finance and market development, including the evolving role of ESG considerations in financing decisions and investment flows. He holds a Master of Business Administration (MBA) and a Bachelor of Arts degree and has undertaken executive leadership and banking programmes with leading international institutions.
In a household in Ghana, a mother loads ingredients into a new Up Energy electric cooker to make dinner for her family. Within minutes, it reaches the boil – far faster than the charcoal she once used – while a sensor in its base quietly records the event. Across hundreds of thousands of homes, readings like these could add up to something finance is only now beginning to measure directly: how households cook. The data would travel from the kitchen to a verification registry, where it would generate carbon credits recognised by the Ghanaian government under the Paris Agreement. Those credits, once purchased by Switzerland through the KliK Foundation, would help determine the returns paid to impact investors on a bond sold in London and held from Toronto to Copenhagen.
This is the future that the USD 200 million Clean Cooking Outcome Bond, issued by the International Bank for Reconstruction and Development (IBRD) at the World Bank in December 2025 and structured by our bank, Standard Chartered, is designed to finance. The first outcome bond to link investor returns to carbon credits generated under Article 6.2 of the Paris Agreement, it will frontload about USD 30.5 million to support the distribution by UpEnergy of some 415,000 cleaner cookstoves across Ghana by 2028. This ties directly to Ghana’s national climate goal of 50% clean cooking access by 2030. Electric cookers go to homes with grid power, and locally made efficient stoves go to households still cooking on charcoal. Over 60% of Ghanaian households cook with wood or charcoal today. Globally, women and children bear much of the burden of household air pollution. A cleaner stove is therefore a health measure, a step towards gender equity and a climate instrument at once. It is now also an asset that global investors can price.
What makes this transaction significant is not the cooker but the system beneath it. A bond like this is possible only because Ghana has spent most of a decade building the architecture to measure, verify and finance climate outcomes: a legally recognised carbon registry, a national green finance taxonomy, climate-risk rules for financial institutions, and a cross-sector Sustainable Finance Roadmap launched in 2026. Ghana’s ESG market is entering a new phase, from regulatory design to transaction execution. For banks, that changes the task at hand. Sustainability is no longer a reporting exercise at the edge of the balance sheet; it is increasingly a question of which institutions can originate credible projects, convert data into risk insight, and fund measurable transition outcomes. This article shares Ghana’s journey, and what can be learned from it.
ESG has moved from the margins of banking to the centre of how decisions are made in Ghana. Four forces have driven the change. Regulation has brought sustainability into governance, credit assessment and supervisory reporting. International investors increasingly judge emerging-market exposures through an ESG lens, so credible disclosure has become a condition of access to global capital. Climate shocks, from floods to prolonged dry spells, damage collateral and household incomes, which exposes the vulnerability of borrowers in agriculture and related sectors. Customers, regulators and communities now expect banks to show that their lending supports environmental protection, social inclusion and long-term resilience.
The investor dimension is sharpening as global disclosure standards converge. The baseline set by the International Sustainability Standards Board is reshaping what international allocators expect to see. Banks in Ghana that report credibly against recognised frameworks can widen their access to crossborder funding, development finance and sustainability-linked capital. Weak or inconsistent disclosure increasingly does the opposite. For us, the conclusion is straightforward. Sustainability is no longer a reporting obligation managed at the periphery. It shapes asset quality, funding access and competitive position.
This case is not universally accepted. In parts of the global market, ESG has drawn a backlash. Critics argue that it distracts management from commercial fundamentals and loads cost onto institutions that can ill afford it. A version of that argument is heard closer to home, where some smaller banks say the pace and volume of new expectations risk outrunning their capacity to absorb them. The concern is a fair one. The costs are real, but they are the costs of measuring risk that already sits on our books. The answer is to make measurement and compliance cheaper and more widely shared. What can be learned from Ghana’s journey so far?
Ghana’s regulators have implemented a sequence of frameworks that, together, are reshaping how banks assess risk, allocate capital and report performance linked to sustainable assets and activities. The change has been deliberate and cumulative rather than sudden.
The foundation is the Bank of Ghana’s Sustainable Banking Principles, adopted in 2019. The central bank has mandated that commercial lenders formalise their environmental risk frameworks, embedding sustainability considerations directly into daily loan underwriting, portfolio oversight and high-risk client scrutiny.
The Principles are voluntary, yet all 23 commercial banks have endorsed them. Industry compliance reached an average of 73 per cent by September 2025, measured under a standardised framework the central bank developed in 2021 with the International Finance Corporation and Switzerland’s State Secretariat for Economic Affairs. Their origins trace to a multi-stakeholder committee formed in 2015, so this is the product of nearly a decade of steady work. Some argue that this voluntary approach is too permissive to change behaviour. Our view is that the voluntary route bought something valuable, which is genuine industry ownership rather than grudging compliance. The Bank of Ghana has since turned voluntary guidelines into binding mandates under the 2024 Directive. It now requires banks to treat climate as a core threat and undertake scenario analysis and stress testing.
The most important recent step came in June 2026: the unified Sustainable Finance Roadmap. Jointly developed by the central bank and its sister regulators, it breaks down silos and aligns ESG standards across banking, insurance, capital markets and pension sectors. For the first time, a single framework now coordinates ESG and climate-risk standards across banking, insurance, pensions and capital markets. This marks a shift from institution-by-institution progress towards regulatory convergence. As the central bank has stressed, its value will be proven in implementation.
Other measures extend the architecture beyond the banking regulator. The Ghana Stock Exchange’s ESG Disclosures Guidance Manual sets standardised reporting across the environmental, social and governance pillars, drawing on the Global Reporting Initiative standards. Launched by the Ministry of Finance in October 2024, Ghana’s Green Finance Taxonomy defines environmentally sustainable work across priority sectors including energy, agriculture, forestry, water, waste, construction and transport. The Securities and Exchange Commission released its Green Bond Guidelines in the same year to set clear standards that open a trusted path to market for labelled debt instruments.
The environmental side of this architecture rests on the Environmental Protection Act, 2025 (Act 1124), which places Ghana’s carbon-market ambitions on a statutory footing. The Act establishes the Ghana Carbon Registry, a Carbon Markets Office and rules for monitoring, reporting and verification. This is the machinery that allowed the Clean Cooking Outcome Bond to generate credits with international integrity under Article 6.2. Without this statutory foundation, the transaction could not have taken a form that global investors would recognise or trust.
Climate risk is increasingly material to borrower resilience, collateral values and credit performance. Banks are expected to bring it into the heart of credit governance, through climate scenarios, sector level exposure analysis and clear mitigation strategies. The Sustainable Banking Principles call for enhanced due diligence in higher-risk sectors such as agriculture, forestry, energy, construction and extractives. For larger exposures in these sectors, site visits, management interviews and verification of permits are becoming standard practice.
As supervisory expectations mature, banks will need to show more than an ability to identify climate exposures. They will need to show that they are planning for transition, through client engagement, sector strategies and, in time, climate stress testing of their portfolios. For institutions with concentrated exposure to climate-sensitive sectors, this is becoming a core risk-management discipline.
Supply-chain sustainability is now a credit issue in its own right. Ghana’s cocoa and timber exporters face tightening scrutiny under the European Union’s deforestation-free supply chain rules, whose main obligations apply to large operators from 30 December 2026. Banks that lend across agribusiness value chains must therefore treat supply-chain due diligence and land-use monitoring as central to credit risk, because clients’ access to key export markets increasingly depends on it. This is familiar ground for us, given our long history financing Ghana’s agriculture and commodities sectors.
The Green Finance Taxonomy identifies renewable energy, clean transport, water infrastructure and climate-smart agriculture as priorities for green and transition finance. Ghana has not yet issued a sovereign green bond, and the absence of a domestic benchmark remains a gap. Even so, the clarity the taxonomy provides supports labelled instruments that can attract sustainability-aligned investors. The Clean Cooking Outcome Bond shows that internationally credible, climate-linked structures can now be built around Ghanaian projects.
Sustainability in Ghana reaches well beyond the environmental agenda. Climate shocks fall hardest on low-income households and informal enterprises, weakening collateral and repayment capacity.
Inclusive green finance seeks to break that cycle. Instruments such as green microcredit, climate-linked insurance and resilience-focused savings can widen access to finance while supporting adaptation.
A cleaner cookstove shows why the environmental and social agendas cannot be separated. It improves household air quality and health. It returns time once spent tending a charcoal fire. It lowers fuel costs. And it reduces emissions. A single intervention delivers health, gender and climate benefits together. That is what makes clean cooking as much a social investment as an environmental one.
Across the country, the shift to cleaner cooking is changing daily life in different ways. In Assin Odumase, a town in Ghana’s Central Region, Cynthia Arthur explains how electric cooking has transformed both her budget and her day. “The first benefit is the money I save,” she explains. “When I was cooking with charcoal, I was constantly spending more than I realised. Now, with the electric pressure cooker, cooking has become much more affordable.” The speed of the cooker has also changed her routine. “Even when I’m running late for work, I can still prepare a meal because I know the pressure cooker cooks everything so quickly.” Equally important are the health and safety improvements. Charcoal cooking filled her kitchen with smoke and exposed her to burns from open flames; electric cooking provides a cleaner and safer environment. “With the pressure cooker, I no longer have to worry about smoke or dirtying my kitchen walls,” she says, highlighting how clean cooking technology is improving both household cooking and family well-being.
The Sustainable Banking Principles give this social mandate concrete form. They prioritise lending to small and medium-sized enterprises, women-owned businesses and youth enterprises, and they encourage gender-sensitive policies and inclusive product design. Responsible lending matters here too. As banks extend credit to less-experienced borrowers, clear terms and fair treatment protect consumers and sustain trust. In an economy where micro, small and medium-sized enterprises account for most employment, serving these segments well is both a development priority and a commercial opportunity.
Digital channels make this achievable at scale. Ghana’s progress in mobile money and digital payments has already extended access well beyond the branch network. The same channels can carry climate-linked insurance, resilience savings and green microcredit to underserved households at viable cost, as demonstrates Up Energy by their use of this technology in the deployment of their cookstoves, financed under the Clean Cooking Outcome Bond.
Technology is changing how ESG performance is measured, monitored and assured. A sensor-enabled cookstove is one example. Connected devices now allow near real-time verification of climate benefits, which is what lets cooking data support carbon reporting. Geospatial analysis and remote sensing support deforestation monitoring and land-use verification. The Bank of Ghana’s supervisory digitalisation aims to improve data quality and harmonise reporting across licensed institutions.
There is a debate here that our industry should not sidestep. Carbon markets have a credibility problem. A 2024 study in Nature Sustainability assessed the methodologies behind most cookstove credits issued to date and estimated that the projects it sampled were over-credited by a factor of around nine. Certifiers have contested that finding. But it reflected a real weakness, because claimed reductions have too often rested on assumptions about how often a stove was used rather than on evidence of use.
The same study points towards the remedy. It found that the metered approach, which monitors fuel use directly, was the most accurate of those assessed by a wide margin. That is the kind of sensor-based monitoring used in the projects this bond supports. When a device records actual cooking events, a credit rests on data rather than an estimate.
These tools raise the standard of information, and they raise the bar for banks. Institutions must invest in data systems, analytical capability and cybersecurity. They also need people who can read climate risk data and taxonomy-aligned metrics and turn them into lending decisions. We see this capability as a source of competitive advantage, not simply a compliance cost. The banks that can measure and verify credibly will be best placed to originate and fund the transactions that follow. Data scarcity and inconsistent quality remain the main obstacles and closing that gap is where much of the work now lies.
Governance sits at the centre of this agenda. The frameworks now in force push accountability for environmental, social and climate risk up to board and senior-management level. They treat diversity and inclusion as governance matters rather than peripheral commitments. The Sustainable Banking Principles expect board-approved policies and clear internal ownership. The climate-risk directive and the strategic plan expect boards to understand how climate exposures affect the institutions they oversee.
Boards that treat ESG as a standing part of strategy and risk oversight will be better placed to earn the confidence of regulators, investors and clients. That means defined ownership, meaningful metrics and honest reporting. The convergence signalled by the Sustainable Finance Roadmap raises the stakes further. As expectations align across banking, insurance, pensions and capital markets, inconsistent governance will be harder to justify.
Real obstacles remain. ESG and climate data are still patchy, and smaller institutions in particular face meaningful costs in building the systems and skills that good implementation requires. Specialist capability is scarce across the market. Across most of Africa, the pipeline of bankable green projects is still thin. Without a sovereign green benchmark, pricing and structuring labelled instruments is harder than in more developed markets. Macroeconomic and currency conditions can constrain the long tenors that green and transition finance often need.
The direction of travel is nonetheless clear, and the priorities for banks follow from it. ESG and climate considerations belong in board oversight, risk appetite and long-term strategy. Investment in data systems, geospatial tools and climate-scenario modelling will be decisive for accurate risk assessment. Outcome-based structures such as the Clean Cooking Outcome Bond point to a growing pool of investors seeking measurable impact. Partnerships with development finance institutions, climate funds and carbon-market participants will be essential to scaling this work. Above all, banks should work alongside clients on their sustainability and supply-chain strategies rather than treat ESG as a compliance overlay.
At Standard Chartered, we see Ghana’s sustainable finance market entering a phase of consolidation, in which a deacade of reform begins to shape everyday banking. We intend to help lead it. The task is to mobilise capital, manage climate risk and finance the country’s transition to a low-carbon and inclusive economy. The Clean Cooking Outcome Bond shows what is possible when a Ghanaian project is measured, verified and financed to an international standard. The next phase will be won by institutions that turn standards into origination, data into risk insight, and climate ambition into financed outcomes. For many households and communities across Ghana, the value of this market will be judged not by the frameworks written but by the outcomes delivered.