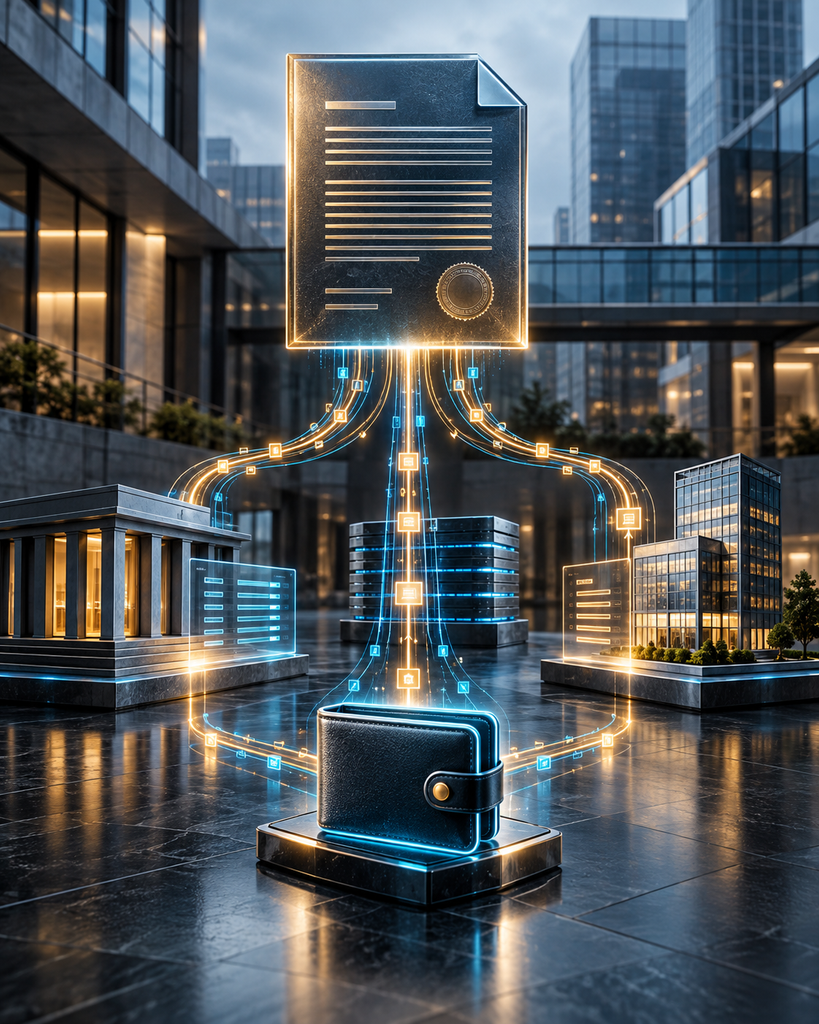

Ukraine has brought most of Law No. 4833-IX into force, turning a six-month preparation period into a live test of digital debt recovery. From 23 October, the country’s Automated Enforcement Proceedings System can interact more comprehensively with banks, non-bank payment service providers and electronic-money issuers. Enforcement officers can trace accounts and electronic wallets, apply lawful freezes and direct funds towards a debt under an existing enforcement order. When a debt and associated charges are paid, the system should also remove account restrictions more quickly.
This is not merely a paperless administrative upgrade. The reform closes a gap between traditional bank enforcement and a payments market that increasingly includes fintech accounts and electronic money. It also changes the treatment of term deposits held by registered debtors and strengthens checks against the Unified Register of Debtors before certain property transactions. For lenders and investors, the relevant question is whether those tools reduce the time, leakage and uncertainty involved in converting a legal claim into cash.
That question matters in a market where credit risk remains unevenly distributed. National Bank of Ukraine data show that the system-wide non-performing-loan ratio fell sharply to 11.52 per cent by 1 September 2026. The improvement is substantial, but the corporate NPL ratio was still 13.87 per cent, and industry data point to a heavier burden in state-owned banks. Better enforcement can support recoveries on legacy exposures and make future collateral more credible even when the headline ratio is falling.
What the law changes
Law No. 4833-IX was adopted on 7 April and officially published on 23 April. Its transitional provisions gave financial institutions and public bodies six months to adapt their information systems. The Western Interregional Directorate of Ukraine’s Ministry of Justice says most provisions fully apply from 23 October.
The central change is a broader electronic chain between enforcement officers and the financial system. Banks, payment institutions, non-bank payment providers and electronic-money issuers may be required to identify a debtor’s funds through the automated system. Once the necessary legal decision has been made, electronic money can be converted into conventional funds and transferred to the special account used by the enforcement service or a private enforcement officer.
The law also prevents a term deposit from becoming an indefinite shelter. When the depositor is in the Unified Register of Debtors and the bank has received the relevant enforcement decision, the deposit term cannot be rolled over. At maturity, funds may be directed towards the liability. Separately, notaries, registrars and other authorised bodies must check the debtor register before specified transactions involving property, and information about an attempted transfer can flow back to the enforcement system.
There are counterweights. A creditor still needs a valid enforcement document, an open proceeding and a lawful decision by the responsible officer. The reform does not allow a bank to decide unilaterally that a disputed private claim should be debited. Protected social and targeted payments remain subject to special rules. The threshold below which a debtor’s sole home is generally protected rises from 20 to 50 minimum wages, subject to exceptions including mortgage collateral and compensation for specified harms.
Why faster recovery can change credit pricing
Credit prices reflect expected loss, not only the probability that a borrower defaults. Recovery value and the time needed to obtain it are the other side of the equation. A claim that takes years to trace and enforce is worth less than one supported by reliable account discovery, prompt restraint of assets and predictable release procedures. By covering e-wallets and non-bank payment accounts, Ukraine digital debt enforcement narrows the space in which funds can move beyond traditional bank searches.
If the system works consistently, banks may be able to shorten workout periods and reduce legal and operational costs. That could improve the economics of selling distressed exposures, because potential buyers can model a more credible route from judgment to cash. It can also strengthen the value attributed to collateral and guarantees when lenders originate new credit. The effect would be incremental rather than immediate, but it touches provisioning, recovery assumptions and risk appetite across the market.
The EU has already treated the measure as part of Ukraine’s programme to improve debt collection and debt treatment and to create conditions for a functioning NPL market. The International Monetary Fund has separately highlighted the need to strengthen bank workout capacity and promote a secondary market for bad loans. Law No. 4833-IX does not complete that agenda by itself, but it supplies part of the enforcement infrastructure on which the agenda depends.
Banks and payment firms bear the execution burden
The immediate costs fall on institutions that must connect systems, respond to structured requests, distinguish attachable from protected funds and preserve accurate audit trails. Traditional banks have experience with account restraint, but the law extends the operational perimeter to payment institutions, fintech platforms and electronic-money issuers. Smaller providers may face proportionately heavier integration, compliance and customer-service costs.
Automation also concentrates operational risk. An incorrect identity match, duplicated proceeding or delayed release can block a legitimate customer’s access to money. The law’s automatic unfreezing mechanism is therefore economically important, not simply consumer friendly: it limits the period in which resolved debts continue to impair account use. The single-enforcement-proceeding approach should reduce duplicate freezes when an old matter is resumed, but implementation will depend on clean data and consistent behaviour by public and private officers.
Likely winners and losers
Banks with large corporate or legacy problem portfolios are the clearest prospective beneficiaries. More efficient asset discovery may lift recoveries and free management capacity, while a better workout environment could support the eventual sale of distressed loans. Specialist investors and servicing firms may also benefit if improved enforcement makes cash-flow timing less opaque. Performing borrowers could gain over time if lenders translate lower recovery uncertainty into more credit or better terms.
Debtors who have relied on fragmented payment accounts, e-wallets or repeated deposit rollovers lose room to delay execution. Payment firms and e-money issuers become active nodes in the enforcement system and incur new operating obligations. Consumers whose funds are misclassified may face disruption, particularly where salary or social-payment accounts are not automatically recognised as protected. Creditors, meanwhile, will not benefit equally: asset scarcity, wartime destruction and court capacity can still limit real recoveries even when the information flow improves.
Implementation timeline and market signals
The operative milestone is 23 October 2026, six months after official publication. Some provisions were phased earlier, but this date brings the main financial-system integrations and procedures into force. Institutions have had a transition period; the next phase is observable performance rather than further legislative design.
Market participants should watch four indicators. First is the speed and accuracy with which banks and payment providers answer automated requests. Second is the time between full payment and release of an account restriction. Third is the recovery rate and duration for bank and purchased-credit portfolios, especially corporate exposures at state-owned banks. Fourth is whether distressed-loan sales broaden beyond isolated transactions as investors gain confidence in enforcement outcomes.
The main risks and open questions
The reform’s strongest claim is procedural: it should make existing lawful enforcement faster and harder to evade. It cannot manufacture assets where war has destroyed productive capacity, repair weak court judgments or eliminate disputes about ownership and priority. Cyber resilience and data quality are central because the system links sensitive records across public authorities and private providers. A technical failure could create both financial harm and public distrust.
There is also a distributional tension. Better creditor rights can support lending, but overly aggressive or erroneous execution can intensify hardship and weaken confidence in formal finance. The higher sole-home threshold and protected-payment rules recognise that tension. Their effectiveness will depend on whether customers can demonstrate protected status quickly and whether appeal and correction channels work at the speed of the automated system.
What comes next
Ukraine has moved an important part of debt enforcement from a fragmented search process towards an integrated financial network. The reform is capable of changing recovery economics because it reaches the places where money is now held, including non-bank payment accounts and electronic wallets. For banks, investors and fintech firms, however, the next evidence will come from operating data: fewer duplicated restraints, faster releases, shorter workout periods and recoveries that improve for reasons other than write-offs.
If those signals emerge, Law No. 4833-IX could strengthen collateral credibility and help convert balance-sheet repair into new lending. If they do not, the market will treat the law as another formal upgrade constrained by institutional capacity. The decisive story is no longer passage. It is whether Ukraine’s digital enforcement infrastructure proves accurate, resilient and fair under live conditions.
Sources
- Verkhovna Rada of Ukraine, Law No. 4833-IX
- Western Interregional Directorate of the Ministry of Justice, detailed implementation analysis
- Kyiv Interregional Directorate of the Ministry of Justice, reform overview
- EU implementing assessment of Ukraine’s debt collection and NPL reforms
- National Bank of Ukraine, September 2026 NPL data
- OECD, Stronger Financial Markets and Institutions for Ukraine’s Recovery
S&P Global Market Intelligence, Ukrainian bank asset quality