
Liquid assets are essential components of both personal and business finance. They are assets that can be quickly converted into cash without losing much value. Some examples of these assets include cash, cash equivalents, and marketable securities. Their ability to provide quick access to funds makes them vital for meeting financial obligations.

In personal finance, liquidity ensures individuals can handle unexpected expenses without financial strain. It helps in calculating net worth by showing the portion of assets readily available. Similarly, businesses rely on liquid assets to manage cash flow and settle short-term liabilities, ensuring smooth operations.
For investors and companies, understanding the balance between liquid and illiquid assets is crucial. This balance helps in making informed decisions to optimise financial health. Their role in global markets highlights the importance of managing liquidity effectively.
Key Takeaways
- Liquid assets convert easily into cash.
- Liquidity impacts personal and business finance.
- Managing liquid assets is crucial for financial stability.
Definition and Types of Liquid Assets
Liquid assets are assets that can be easily converted into cash. They provide financial flexibility and security. This section explores three main types: cash and cash equivalents, marketable securities, and money market instruments.
No spam - just the latest insights!
Join over 30,000 industry professionals who subscribe for free



Get exclusive early
access before the official launch
Hear directly from the Big Four advisory firms and leading international law firms on emerging issues
- with our authors given full editorial independence to address the topics that truly matter in each jurisdiction
Cash and Cash Equivalents
Cash is the most liquid asset, including physical currency and funds in checking and savings accounts. Cash equivalents are short-term investments that can be quickly turned into cash with minimal loss of value. They include instruments like Treasury bills and certificates of deposit. Treasury bills are government securities with short maturity periods. Certificates of deposit represent money deposited at banks for a fixed term and earn interest. Both offer safety as they can be liquidated quickly when needed.
Marketable Securities
Marketable securities can be swiftly traded on public exchanges. These include stocks, bonds, and exchange-traded funds (ETFs). Stocks signify parts of ownership in companies and can be sold through the stock market. Bonds are debt instruments issued by corporations or governments, offering periodic interest payments. ETFs are investment funds traded on stock exchanges, much like stocks. They provide liquidity similar to stocks and bonds, and investors can buy or sell them at any time during trading hours.
Money Market Instruments
Money market instruments are another category of liquid assets. They include assets like commercial paper, certificates of deposit, and money market funds. Money market funds are a type of mutual fund, investing in high-quality, short-term debt instruments like government or corporate securities. They offer stable returns with low risks and typically paid dividends that can be easily cashed out. These instruments help investors maintain liquidity while earning some return on their investments.
Measuring Liquidity
Understanding how to measure liquidity is essential for businesses and investors. It involves assessing how easily assets can be converted into cash.
Liquidity Ratios
Liquidity ratios help evaluate a company’s capacity to meet short-term obligations using its assets. The Current Ratio measures the ability to cover liabilities with all current assets. It is calculated by dividing current assets by current liabilities. A higher current ratio might indicate better liquidity, but sometimes it shows excessive inventory.
The Quick Ratio is more stringent. It focuses only on quick assets such as cash, marketable securities, and accounts receivable. This ratio excludes inventory, offering a clearer picture of a company’s liquidity position. Companies with a high quick ratio usually have a solid cash position and meet debts more easily.
Balance Sheet Analysis
The balance sheet provides vital insights into liquidity. Analysts examine the balance sheet to assess a company’s Net Liquid Assets, which are current assets minus current liabilities. This figure shows the company’s capacity to cover immediate obligations without liquidating fixed assets.
Moreover, by reviewing a balance sheet, investors can determine the proportion of liquid versus non-liquid assets. A high level of liquid assets, like cash and marketable securities, often signals the company is well-prepared for financial uncertainties. Understanding this helps assess risk levels and financial stability.
The Role of Liquid Assets in Personal Finance
Liquid assets are vital in personal finance for managing short-term obligations and providing financial security. They allow individuals to quickly convert investments into cash, helping to meet unexpected expenses and support various financial goals.
Emergency Funds
An emergency fund is a key component of financial security. It consists of liquid assets that can be easily accessed in times of crisis.
Commonly found in a high-yield savings account, these funds help households cover sudden expenses like medical bills or car repairs. Importantly, an emergency fund should cover three to six months’ worth of living expenses. This cushion helps individuals avoid taking on debt when faced with short-term financial challenges.
Having an emergency fund ensures peace of mind and financial stability during uncertain times.
Financial Planning
In financial planning, liquid assets play a significant role in balancing immediate needs with long-term goals. By holding a portion of assets in liquid form, individuals are better equipped to handle short-term obligations without disturbing long-term investments.
Liquid assets also provide flexibility, allowing adjustments to meet changing personal goals. They enable regular contributions to retirement accounts or investment portfolios, aligning financial resources with future aspirations. Financial planners often recommend maintaining a careful balance between liquid and non-liquid assets, enabling effective cash flow management and supporting overall financial health.
Investment Strategies
Effective investment strategies involve a blend of liquid and non-liquid assets to meet both short- and long-term objectives. Investors favour liquid assets for their ability to quickly convert into cash without losing value. This provides an opportunity to seize market changes or adjust to financial needs.
A diversified portfolio with the right mix of liquid assets ensures accessibility while allowing participation in potentially more rewarding investments. In retirement planning, maintaining some liquidity enables withdrawal flexibility without derailing the entire investment strategy. By prioritising liquidity, investors can confidently manage risks and adapt strategies to suit personal financial goals.
Liquid Assets in Business and Corporate Finance
Liquid assets play a crucial role in ensuring a business’s financial stability. They allow companies to manage daily operations smoothly and also assess their overall financial health.
Operational Liquidity
Operational liquidity refers to a business’s ability to meet short-term obligations using its liquid assets. Cash flow management is essential, as it ensures that companies can cover operational expenses like salaries, rent, and utilities.
Accounts receivable and inventory are key components of operational liquidity. Quick collection of accounts receivable ensures cash is readily available. Efficient inventory management prevents overstocking, which can tie up funds. Utilising cash and easy-to-access marketable securities offers additional security against unexpected expenses, making it easier for businesses to maintain seamless operations.
Financial Health and Solvency
The financial health of a company is reflected in its ability to meet long-term obligations, a measure often determined by solvency ratios. High liquidity boosts a firm’s solvency, providing reassurance to creditors and investors. This is particularly important during financial stress, as it demonstrates resilience and reliability.
Robust management of liquid assets involves monitoring cash flow and keeping solvency ratios at healthy levels. It also requires accurate assessment of accounts receivable and timely adjustment of inventory levels. Maintaining an optimal balance of liquid assets allows companies to plan for growth and navigate economic fluctuations confidently.
Comparison between Liquid and Illiquid Assets

Understanding the differences between liquid and illiquid assets is crucial for sound financial planning. Liquid assets can be converted to cash quickly without a loss in value, while illiquid assets, like real estate and private equity, often take more time and may involve a loss in value during conversion.
Characteristics and Differences
Liquid assets include cash, money in savings accounts, and short-term investments. They can be turned into cash easily, making them ideal for immediate financial needs. Characteristics include high marketability and low transaction costs.
In contrast, illiquid assets such as real estate, land, collectibles, and private equity are harder to sell. These assets often require significant time or effort to convert into cash. For example, real estate investments might require finding a buyer and navigating legal processes. Illiquid assets are typically held for longer periods due to their potential for growth and stability, despite their lower flexibility in quick cash conversion.
Converting Assets to Cash
Liquid assets are preferred for their quick convertibility. Cash, savings, and money market accounts are examples that offer ease of access. Selling these assets usually incurs minimal fees and can be done within a short timeframe.
On the other hand, converting illiquid assets like land or art involves longer wait times, negotiations, and possibly waiting for market conditions to be favourable. The process might also involve price discounts to attract buyers. Private equity investments may require waiting until the investment matures or a potential buyer is found. The potential loss in value and the time-consuming process highlight their non-liquid nature.
For a practical example, see the difference between liquid and illiquid assets for more insights.
Liquid Assets in the Market

Liquid assets hold significant value due to their ease of conversion into cash. These assets typically have reliable estimates of market value and can be traded efficiently in established markets.
Estimating Market Value
The market value of a liquid asset can often be determined with precision. Publicly traded stocks, for example, are regularly valued based on stock market prices. This ongoing pricing provides a reliable estimate of an asset’s worth.
The value of Treasury bills is also clear, as these are traded regularly and have stable demand. For some assets, estimates may include examining recent transactions of similar assets. It’s essential that the valuation reflects current economic conditions, ensuring accuracy in asset management. This understanding of market value aids investors in making informed decisions.
Established Markets and Trading
Established markets such as stock exchanges provide a platform for trading liquid assets. These markets ensure that there are always buyers and sellers, which simplifies the transfer of ownership. Publicly traded stocks benefit from this setup because ownership can change hands swiftly and with minimal risk.
Moreover, money market instruments also enjoy similar trading conditions. For businesses and investors, having assets in established markets provides stability and reduces liquidity risk. Accessible trading platforms offer transparency and support efficient market operations, ensuring fair pricing and steady demand.
Risks and Considerations

Liquid assets provide flexibility and ease of access for addressing immediate financial needs. However, they come with considerations such as market risks and the impact of various economic factors. Understanding these aspects is crucial for making informed decisions.
Market Risk and Returns
Market risk relates to the potential that the value of liquid assets might fluctuate due to changes in the broader market environment. Assets like stocks may be highly liquid, yet are subject to price changes. A trade-off often exists between liquidity and return, with liquid assets typically offering lower returns compared with less liquid ones, such as real estate or private equity. The stability of liquid assets depends on market conditions, which can affect their resale value and attractiveness.
Investors often seek low-risk options such as government bonds or treasury bills. While these assets are considered stable, their potential returns are usually modest. This balance of liquidity versus potential return must be evaluated regularly to align with individual risk tolerance and investment goals.
Economic Factors Affecting Liquidity
Economic conditions can greatly influence the liquidity of assets. During an economic downturn, liquid assets might be in higher demand, potentially affecting their supply and value. Inflation is another crucial factor, as it can erode the purchasing power afforded by cash or cash equivalents.
At times of high inflation, the relative value of liquid assets decreases as the purchasing power weakens. This necessitates careful consideration of inflation rates when holding large amounts of cash. Investors need to monitor economic indicators to adjust their asset allocation, ensuring liquidity levels meet both short-term needs and long-term objectives.
Global Influence and Currency

Liquid assets play a crucial role in shaping financial markets and economies worldwide. They affect foreign exchange rates and influence global financial stability and economic cycles.
Foreign Currency and Exchange Rates
Foreign currency is essential to international trade and investment. It impacts exchange rates, which determine the value of one currency against another. These rates fluctuate based on factors like interest rates, economic stability, and market speculation.
Money market accounts hold significant volumes of foreign currency. These accounts are integral to managing short-term liquidity needs, allowing individuals and businesses to access and convert funds efficiently. Their role in currency exchange is critical for traders and investors seeking opportunities in global markets. The interplay between foreign currency, exchange rates, and money market accounts underscores their collective impact on international economic dynamics.
Advanced Liquid Assets and Derivatives
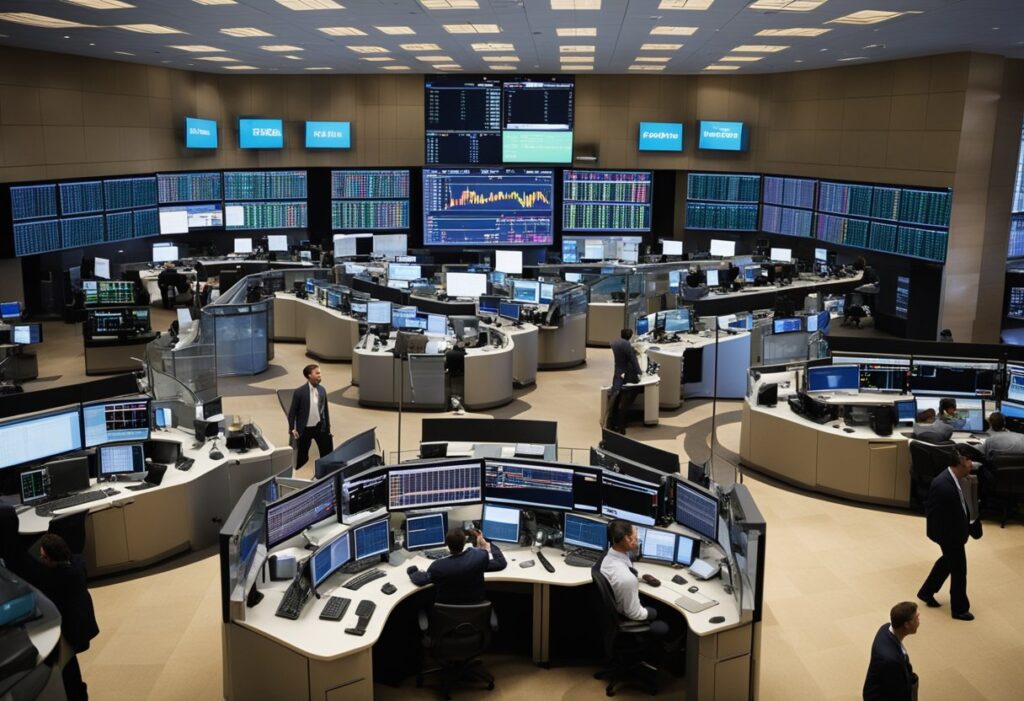
In financial markets, advanced liquid assets often include derivatives and various complex financial products. These tools allow investors to engage in sophisticated trading and risk management strategies by providing more options and flexibility.
Derivatives and Trading Instruments
Derivatives are financial contracts that derive their value from an underlying asset, such as stocks, bonds, or commodities. Stock options, for example, give the holder the right to buy or sell a stock at a predetermined price, which can be useful for hedging or speculative purposes. Treasury notes and U.S. Treasuries are often involved in derivative markets, providing stability and liquidity.
Trading instruments like futures and options allow investors to speculate on price movements without holding the actual asset. This can be beneficial for managing risk and capitalising on market opportunities. Futures contracts, another derivative, obligate the buyer to purchase an asset at a set price in the future, which offers protection against price fluctuations.
Complex Financial Products
Complex financial products include a variety of advanced tools that combine multiple assets or strategies. Index funds and preferred shares are examples where derivatives might be involved to enhance returns or manage risk. Index funds may use futures or options to track an index more closely, while preferred shares can provide fixed income with added layers of protection using derivatives.
Commercial paper is another instrument sometimes linked to derivative strategies. As a short-term debt tool, it can be bundled with derivatives to mitigate default risk. Financial instruments like swaps and forwards also fall into this category, providing additional layers of complexity for investors seeking customised investment solutions.
Conclusion
Liquid assets play a crucial role in ensuring financial stability and flexibility. They allow individuals and businesses to respond quickly to financial needs. By having readily available funds, they can cover emergency expenses or seize investment opportunities without delay.
Importance of Liquid Assets
Liquid assets are vital for maintaining sound financial health. They provide a cushion during financial hardships and help in managing daily expenses efficiently. This liquidity means obligations like debt repayment can be addressed promptly, reducing the risk of financial distress.
Debt Repayment
Quick access to cash helps in meeting short-term liabilities. This makes debt repayment more manageable, preventing late fees or interest charges that could escalate financial burdens.
Financial Flexibility
Possessing liquid assets enables individuals and businesses to adapt to changing circumstances. They offer the freedom to make strategic financial decisions without being held back by illiquid investments or assets that cannot be promptly converted into cash.
In summary, liquid assets are an integral part of a robust financial strategy. They are essential for financial flexibility and security. Prioritising liquid assets ensures readiness to face financial challenges and opportunities with confidence.
Frequently Asked Questions
Liquid assets can be quickly converted into cash, making them vital for meeting short-term financial needs. Differences between liquid and non-liquid assets, methods of classification by banks, and the role of accounting practices in assessing liquidity are examined, along with the status of stocks and precious metals.
What examples can be cited as liquid assets?
Liquid assets include cash and cash equivalents, such as savings accounts and money market funds. Securities like stocks and bonds are also frequently considered liquid assets due to their ability to be sold on exchanges with ease.
How are non-liquid assets different from liquid assets?
Non-liquid assets are harder to convert into cash without losing value or taking considerable time. Examples include real estate and physical property, which may require lengthy processes for sale, compared to the readily available nature of liquid assets.
In what way do banks classify assets as liquid?
Banks consider the ease and speed at which an asset can be turned into cash. Assets like cash itself, marketable securities, and highly stable savings account balances are generally classified as liquid by banks owing to their immediate accessibility.
How is liquidity assessed in accounting practices?
In accounting, liquidity is assessed by evaluating an asset’s ability to be converted into cash and its relative stability in value. Ratios such as the current ratio and quick ratio are typically used to measure liquidity by comparing liquid assets to short-term liabilities.
Can stocks be regarded as liquid assets?
Stocks are usually regarded as liquid assets because they can be sold on stock exchanges fairly rapidly. Their liquidity depends on market conditions and trading volumes, influencing how quickly they can be cashed in.
Is it appropriate to consider precious metals, such as gold, liquid assets?
Precious metals like gold are somewhat liquid due to their market value and ease of sale. Gold can be traded with relative ease, but it may not convert into cash as promptly as other liquid assets like stocks or cash equivalents.
