A legal distinction with commercial weight
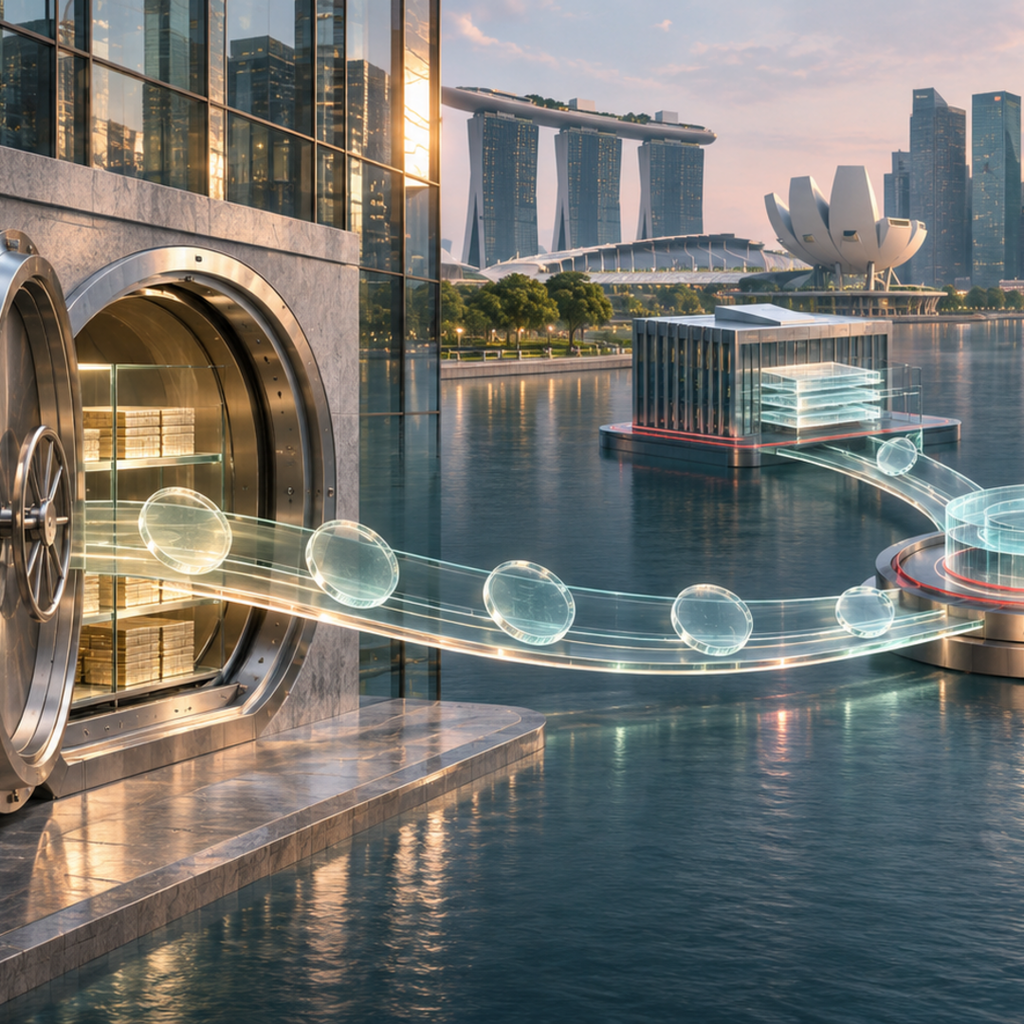
Singapore has given banks a practical regulatory test for deciding when money represented on distributed ledgers remains a bank deposit. The Monetary Authority of Singapore issued its Guide on the Tokenisation of Bank Deposits on 18 November 2026, clarifying that legal and economic substance, rather than the technology or product label, determines whether a digital token qualifies as a deposit under the Banking Act.
That sounds technical, but it addresses one of the central competitive questions in digital finance. Tokenised bonds, funds and collateral need a trusted settlement asset. Banks want their own deposit liabilities to fill that role because deposits already sit inside familiar prudential, insolvency and resolution frameworks. Stablecoin issuers want a parallel role, while central banks are developing wholesale digital money for interbank settlement. Singapore’s guidance defines the conditions under which commercial-bank money can move onto programmable rails without losing its legal character.
The timing makes the guidance more than an abstract interpretation. On 19 November, MAS said it had successfully issued S$100 million of tokenised MAS Bills, settled against Singapore-dollar wholesale central bank digital currency. Its managing director also said 24 industry members and policymakers were participating in the BLOOM digital-money platform. In September, DBS, OCBC and UOB completed live domestic Singapore-dollar transactions using tokenised deposits on Swift’s ledger. The regulatory perimeter is therefore being clarified as live infrastructure begins to emerge.
What the Singapore tokenised deposit guidance requires
MAS starts from a technology-neutral premise: putting a claim on distributed-ledger technology does not by itself turn it into a deposit, a security or a cryptoasset. A token may represent an existing deposit, or it may itself constitute a deposit claim. In either case, the account-based relationship between the bank and depositor must remain fundamental.
The authority will consider three characteristics. First, the customer’s repayment right should arise from the terms governing a deposit account rather than solely from possession or control of a token. Secondly, the bank should maintain an ongoing account relationship, know the depositor’s identity and be able to establish the amount owed at any time. Thirdly, transfers should occur with the bank’s consent, either transaction by transaction or under an arrangement agreed in advance.
Those conditions draw a clear boundary around bearer-style instruments. MAS does not expect a token whose repayment right depends only on possession or control to count as a tokenised deposit. Banks must also avoid calling a product a deposit when it does not qualify under the Act, and should engage the regulator early when the characterisation is uncertain.
The guide attaches operational consequences to the legal classification. Issuers should disclose material differences from an equivalent conventional deposit, including deposit-insurance treatment, transfer restrictions, finality and reversibility, error handling, governing records, technology failures, contingency arrangements and fees. If a distributed ledger is the authoritative record of customers’ entitlements, controls should address reconciliation, corrections and the preservation of claims if that record becomes unavailable or unreliable.
Why the account model matters for settlement money
The guide preserves a defining feature of commercial-bank money: a deposit is a liability recorded within a relationship that the bank controls and supervises. This allows identity checks, sanctions controls, transaction monitoring, reversals where the terms permit them and integration with resolution planning. It also means tokenised deposits will not operate like freely circulating bearer assets outside the issuing bank’s perimeter.
For institutional users, the trade-off is meaningful. The account model can make tokenised deposits easier to adopt than an unfamiliar cryptoasset because treasury teams, auditors and risk committees can map the claim back to a regulated bank. It can support programmable payments and near-continuous settlement while retaining established legal rights. But bank consent and account relationships can limit composability, particularly across institutions or open networks.
MAS explicitly recognises demand for cross-bank transfers. Its answer is not to make each token a bearer instrument. Instead, tokenised deposits may remain account-based within their respective banks while a separate interbank arrangement settles obligations between the issuers. That architecture puts interoperability, rather than universal token fungibility, at the centre of the market.
The transmission mechanism into financial markets
The first market channel is settlement risk. Tokenised assets cannot scale if the cash leg is legally uncertain or if ownership records fail to match the money used to settle them. Clear treatment of deposits and authoritative records reduces one source of principal, operational and legal risk. This matters most in repo, collateral management, foreign exchange and securities settlement, where timing mismatches can consume liquidity and capital.
The second channel is bank funding. If corporate treasurers and institutional investors hold more operating balances in tokenised form, deposits can remain on bank balance sheets rather than moving into non-bank stablecoin reserves. Banks would preserve a funding source and gain new transaction revenue, although around-the-clock transferability could also make deposits more mobile in stress. Liquidity models, intraday buffers and contingency arrangements will have to catch up with faster rails.
The third channel is competition over digital money. MAS is developing three layers at once: tokenised bank deposits, regulated stablecoins and wholesale central bank digital currency. The new guide strengthens the deposit layer by specifying how it can retain bank-money status. Stablecoins may still offer broader distribution and cross-platform reach, while wholesale central bank money can provide the lowest-risk interbank settlement asset. The likely outcome is coexistence rather than a single winner, with each form of money serving a different part of the transaction chain.
The fourth channel is market infrastructure. Banks, custodians, exchanges and clearing houses will need common technical and legal standards if a deposit token issued by one bank is to settle an asset held elsewhere. Singapore’s approach favours controlled interoperability. That could channel investment towards permissioned ledgers, interbank bridges, synchronisation mechanisms and common rulebooks rather than public-chain bearer tokens.
Likely winners and losers
Large banks with established transaction-banking franchises are well placed. They already manage corporate deposits, identity controls and liquidity, and can spread the cost of ledger integration across payments, custody and securities services. DBS, OCBC and UOB’s live Swift-ledger transactions show that domestic institutions are moving beyond laboratory tests. International banks can also use Singapore as a hub for cross-border treasury and tokenised-asset services.
Institutional users may benefit from faster settlement, richer transaction data and programmable controls without abandoning a familiar bank claim. Asset managers and dealers could reduce collateral movement delays and operating friction if the cash and asset legs become interoperable. Infrastructure providers that connect otherwise separate bank ledgers also gain strategic importance.
The position is less comfortable for models that depend on anonymous or freely transferable bank liabilities. A bearer-style token cannot rely on the deposit label simply because a bank created it. Smaller banks may also struggle with the technology, liquidity and control costs needed to issue interoperable tokens. Stablecoin providers face a stronger bank-led competitor for institutional settlement, although they may retain advantages in distribution, cross-border availability and operation outside banking hours.
Risks and open questions
The guide is deliberately general. MAS says it does not approve the characterisation of any individual arrangement, and firms remain responsible for their own legal and compliance analysis. Product-by-product uncertainty therefore remains, especially where tokens move between banks, chains or jurisdictions.
Deposit insurance is another sensitive area. The guide says treatment under insurance, insolvency and resolution frameworks follows the instrument’s legal characterisation, but firms must disclose the actual protection available. Users should not assume that every token carrying a bank’s name is insured, or that protection travels unchanged when claims cross borders.
Operational resilience may become the decisive test. An on-chain record can be authoritative, but banks must still explain how they reconcile discrepancies, correct errors and preserve claims if the ledger fails. Smart-contract bugs, key management, cyber incidents and network outages can turn a faster settlement design into a new source of concentrated operational risk.
There is also a macro-liquidity question. Programmability and longer operating hours can improve the use of cash in normal markets, yet they may accelerate withdrawals in stress. Regulators will need evidence from live use before concluding that existing liquidity assumptions remain adequate for deposits that can move instantly across automated workflows.
What market participants should watch next
The Singapore tokenised deposit guidance is a foundation, not an endpoint. The next signal will be whether banks launch products at commercial scale and whether separate bank tokens can interoperate without fragmenting liquidity. The StraitsX, OCBC and Standard Chartered proof of concept announced on 19 November is directly relevant because it tests payments between distinct tokenised-deposit networks.
Participants should also watch how MAS divides roles among tokenised deposits, regulated stablecoins and wholesale central bank digital currency; whether deposit-insurance disclosures become standardised; and whether cross-border supervisors recognise the same account-based claims. The Guardian Tokenised Collateral Framework, published alongside the latest announcements, will show how the money layer connects to collateral eligibility, custody, valuation and enforcement.
Singapore has not declared that bank tokens will replace stablecoins or conventional deposits. It has done something more useful: it has specified the legal and operational properties that bank money must preserve when it becomes programmable. If banks can combine those protections with interoperable, always-available settlement, the guidance could shift tokenised finance from isolated pilots towards a functioning institutional market.
Sources
MAS — Guide on the Tokenisation of Bank Deposits — official guidance issued 18 November 2026
MAS — Advancing the Future of Finance keynote — market architecture and adoption context
MAS — successful issuance of tokenised MAS Bills — S$100 million issuance and wholesale CBDC settlement
UOB — live SGD transactions on Swift’s ledger — live tokenised-deposit transactions
StraitsX — tokenised-deposit network interoperability proof of concept — industry evidence announced 19 November 2026
Axios — Tokenized deposits explained — independent institutional-market context
This article is financial journalism and analysis, not legal or investment advice.