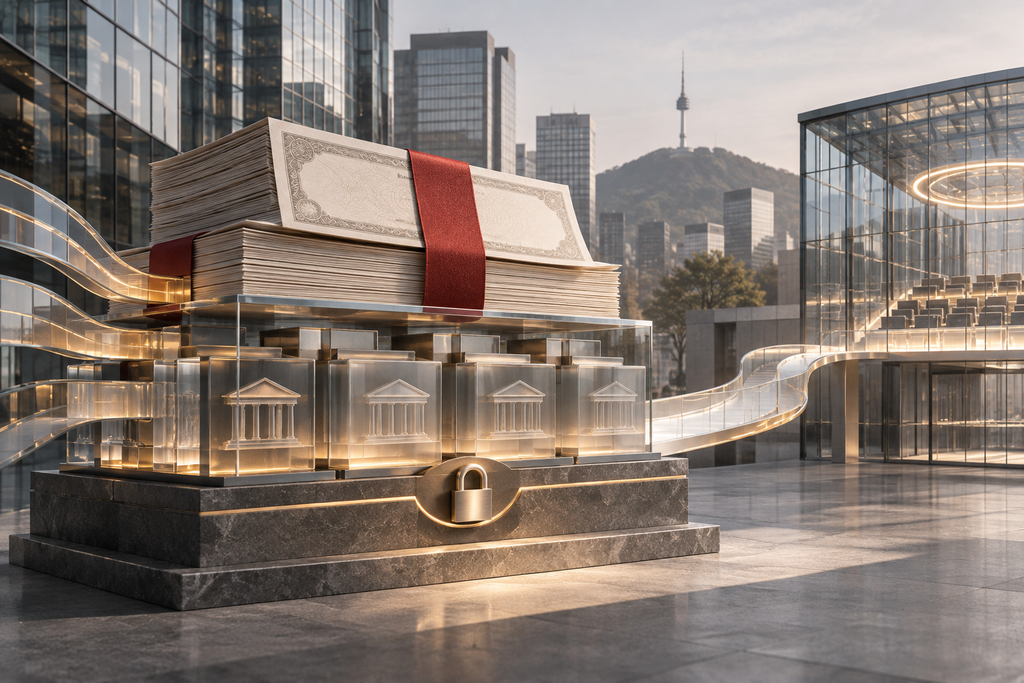
South Korea’s IPO pricing reform takes effect on 13 November 2026, introducing two tools that have long been discussed but were unavailable under the previous framework: preliminary bookbuilding before a securities registration statement is filed, and binding cornerstone allocations to institutions prepared to hold shares for months after listing.
The commencement matters because it changes the mechanics of every eligible KOSPI and KOSDAQ flotation from the start of the deal process. Bookrunners can now test price and volume with qualified institutions before committing publicly to a price range. They can also secure a defined base of longer-duration demand before the wider institutional book and retail subscription open.
That is a direct intervention in the two points at which Korean IPOs have proved vulnerable: valuation ranges set with limited pre-filing market feedback, and a post-listing float exposed to institutions seeking rapid gains. Bloomberg reported the reform as an attempt to curb sharp price falls after listings. The Financial Services Commission, or FSC, frames it as a way to improve valuation and bring medium- to long-term institutions into deals earlier.
How South Korea IPO cornerstone investor rules work
Under the preliminary bookbuilding process, a lead manager must first prepare an IPO due-diligence report. It may then provide prospective information that will later appear in the registration statement to qualified institutions and ask for indications of price and quantity. Private equity and discretionary investment businesses generally need at least KRW30 billion in entrusted assets, together with valuation capability and controls for non-public information.
The information regime is deliberately strict. Lead managers must sign confidentiality agreements with each participant and keep records of when information was supplied, to whom and in what form. Misuse of the information may engage Korea’s material non-public information rules. The mechanism therefore creates an earlier price-discovery window, but not an informal marketing free-for-all.
Cornerstone investors face an additional capacity test. Their equity capital or entrusted assets must be at least 20 times the value of the shares they agree to buy. Half of a cornerstone allocation is locked for six months, 30 per cent for eight months and the final 20 per cent for ten months. The staggered release is intended to prevent one large expiry date from becoming a predictable selling event.
For KOSPI IPOs, cornerstone investors may receive up to 20 per cent of the ordinary institutional allocation in aggregate, with no single cornerstone taking more than 10 per cent of that allocation. That translates into as much as 10 per cent of the entire offer in aggregate and 5 per cent for one cornerstone. For KOSDAQ, the corresponding limits are 30 per cent and 20 per cent of the relevant institutional allocation. Because the institutional pool varies, cornerstones can represent 4.5 to 10.5 per cent of the whole KOSDAQ offer in aggregate and 3 to 7 per cent for one investor.
The rules also bar cornerstone agreements with institutions that have specified special interests, including major shareholders and certain affiliated parties, and prohibit side benefits. Retail allocation is not being displaced: the pre-allocation comes from the institutional tranche.
The transmission mechanism for pricing and liquidity
The first market effect should appear before a prospectus reaches investors. Earlier demand testing gives issuers and banks evidence with which to narrow or reset a proposed valuation range. In weak markets, that may encourage a realistic price rather than a late withdrawal. In strong markets, it may help distinguish durable demand from orders placed mainly to maximise allocation.
The second effect is on the freely tradable supply after listing. A cornerstone does not guarantee a successful debut, but its locked position removes a portion of the institutional allocation from near-term turnover. That can reduce mechanical selling pressure and give analysts and investors more time to assess earnings and strategy before the full allocation becomes tradable. The staggered six-, eight- and ten-month releases distribute that eventual supply over time.
The third effect is competitive. Issuers with credible long-term stories and bookrunners with strong institutional networks may find it easier to assemble cornerstone groups. KOSDAQ companies receive proportionately more room because smaller offers can struggle to attract stable capital. Asset managers capable of fundamental diligence gain an earlier seat in the process, while institutions built around short holding periods lose some relative influence over the anchored part of the book.
The reform lands in a difficult fundraising environment. Korea JoongAng Daily reported that Korean stock issuance totalled KRW5.31 trillion in the first nine months of 2026, the weakest comparable period in at least six years, amid volatility and more demanding scrutiny of share offerings. Better mechanics cannot create risk appetite, but they can alter whether viable issuers proceed and at what price.
Likely winners and losers
Potential winners include issuers willing to accept disciplined valuations in exchange for a more stable register; long-horizon institutions that can tolerate the lock-up; and bookrunners able to conduct robust pre-filing diligence and match companies with credible anchors. Retail investors may benefit indirectly if pricing incorporates institutional feedback earlier and fewer allocated shares are available for immediate flipping.
The trade-offs are real. Cornerstones bear market risk without the ability to exit, and will demand compensation through price, allocation certainty or access to attractive transactions. Institutions outside the selected group may see less of the regular book. Smaller underwriters could face a disadvantage if issuers equate a large cornerstone network with execution certainty. Issuers may also worry that a cool preliminary book becomes a self-reinforcing signal before the public marketing period begins.
For KOSDAQ, a larger permissible share for cornerstones may stabilise smaller deals, but it can also concentrate price-setting power. The conflict rules limit obvious related-party arrangements; they do not remove the softer risk that repeat relationships between banks and large asset managers influence access or valuation.
Implementation and the evidence to watch
The revised Financial Investment Services and Capital Markets Act and its implementing decree are effective from 13 November. The first useful evidence will come deal by deal rather than from a single market-wide cutover. Existing transactions already deep into their timetable may not display the new structure immediately, while newly launched offerings can use both mechanisms from inception.
Market participants should track the share of eligible deals using preliminary bookbuilding, changes between the initial internal valuation and the filed price range, cornerstone take-up by KOSPI and KOSDAQ issuers, and the identity and concentration of repeat anchor investors. First-day returns alone will be a poor test. More revealing measures will include volatility and turnover over the first three months, withdrawal rates, post-lock-up trading around months six, eight and ten, and whether issuers raise more capital without increasing discounts.
One important counterargument is that an anchor can stabilise supply but cannot repair a weak company or an excessive valuation. A locked investor may merely postpone selling. Another is that early institutional feedback could reinforce herd behaviour and push issuers to accept conservative prices. The reform should therefore be judged on the quality of price discovery and the durability of the shareholder base, not on whether every debut trades higher.
What comes next
South Korea’s IPO pricing reform gives banks and issuers more information before filing and gives selected institutions more certainty in return for a meaningful holding commitment. Its market consequence is not a promise of rising IPO prices. It is a reallocation of risk and influence: away from a single late-stage order book and immediate tradability, and towards earlier diligence, negotiated anchor demand and staged liquidity.
The next test is practical adoption. If cornerstone agreements become common, transparent and diversified, they could make the Korean primary market more resilient and help credible companies raise equity in unsettled conditions. If allocations cluster among a small circle of institutions or merely delay weak-market selling, the reform will have changed the timetable more than the economics. The first cohort of post-13 November filings will show which interpretation is closer to reality.
Sources
- Financial Services Commission final implementing rules, 3 November 2026
- Financial Services Commission announcement of the revised Act, 23 April 2026
- Bloomberg report on cornerstone lock-ups and post-IPO sell-offs, 5 November 2026
- Korea JoongAng Daily on the 2026 corporate fundraising slowdown, 9 November 2026
- Korea Capital Market Institute regulatory review, June 2026